947-Acre Sovereign Land & Water Rights Platform
Executive Overview
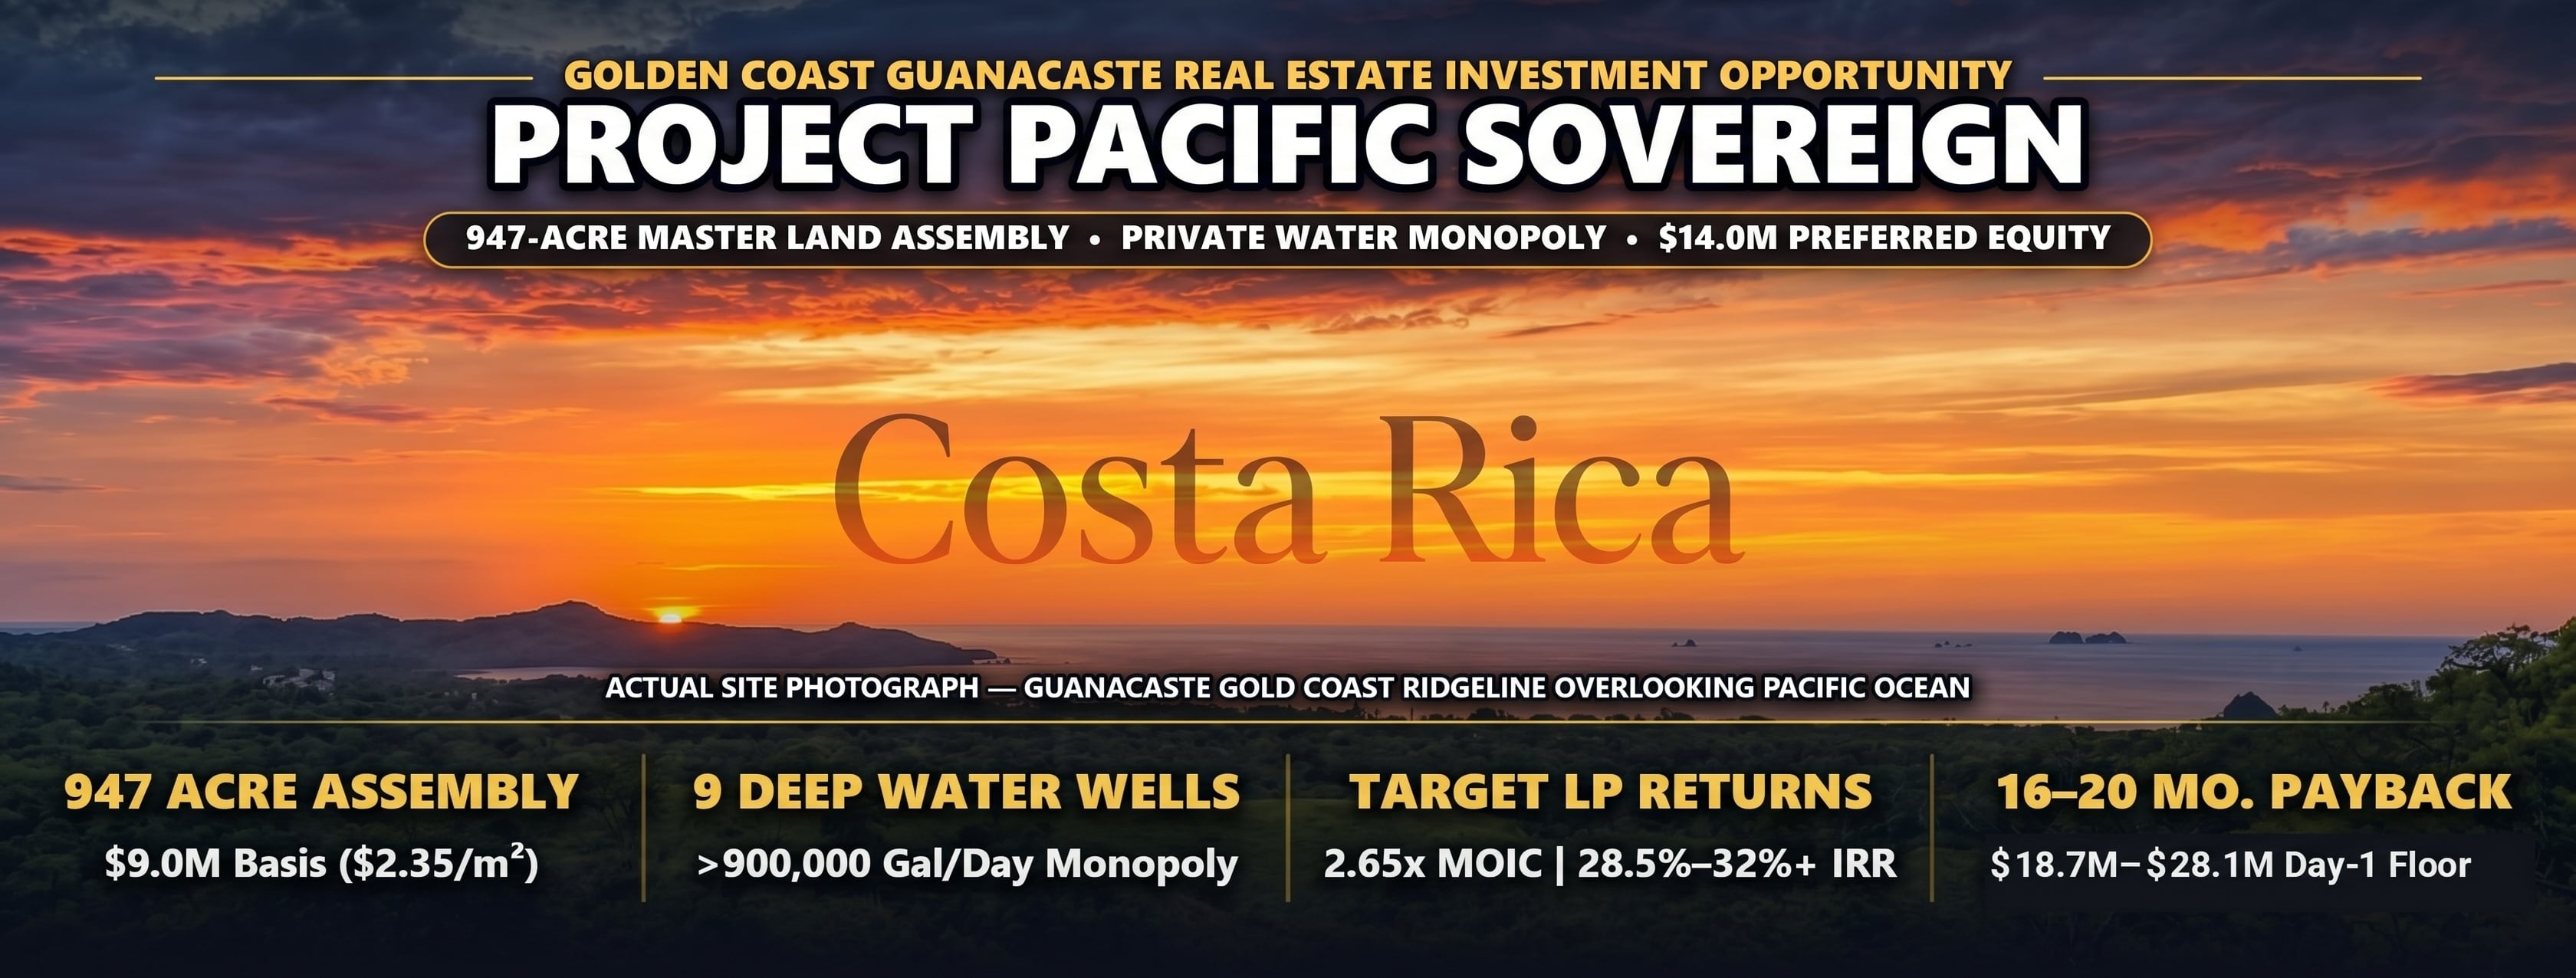
Aria Business Advisors has been exclusively retained to orchestrate the programmatic equity capitalization for Project Pacific Sovereign, a generational 947-acre (383.20-hectare) contiguous landholding and private utility infrastructure platform located along Costa Rica's premier North Pacific Gold Coast in Guanacaste. The underlying real estate and utility assets are secured under a fully executed Purchase & Sale Agreement (PSA) at a wholesale purchase basis of $9,000,000 USD ($2.35/m² | ~$9,500/acre). This contracted entry represents an 80%+ discount to raw inland baseline comps ($25 to $150+/m²) and an approximate 99% discount to adjacent luxury master-planned resort land ($645/m²). We are actively placing $14,000,000 USD in Preferred LP Equity to execute the contracted PSA closing ($9.0M) and fully fund Phase 1 horizontal civil works, 9-well grid activation, and 18-month operational reserves ($5.0M).
Products, Services & Market Positioning
The platform is anchored by four core asset moats: (1) Sovereign Utility Monopoly: 100% control of the operating entity holding 9 fully permitted, registered MINAE deep-water production wells yielding 14.15 L/s active flow (>50 L/s tested yield / >900,000 gal/day), certified by former AyA President Rafael Villalta. In a region constrained by municipal building moratoria (AyA/ASADA freezes), this private infrastructure provides 100% water autonomy for 2,500+ residences and regional commercial off-take leverage. (2) Immediate Day-1 Liquidity: Includes 40 individually titled, shovel-ready horizontal condominium lots acquired at an allocated basis of $31,250/lot vs. retail comps of $90,000 to $160,000+, generating $3.6M to $5.0M in gross cash flow in Months 1 to 18. (3) Pacific Beachfront Concession Anchor: 100% stock transfer of the corporate entity controlling a 20-year sovereign ZMT concession on Playa Brasilito (180 linear meters of direct beachfront). (4) Substantiated Downside Floor: Standalone Sum-of-the-Parts (SOTP) liquidation valuation of $18.7M to $28.1M provides 1.33x to 2.00x Day-1 asset coverage against the full $14.0M raise, substantiated by a documented $20M cash ranch offer.
Operations, Facilities & Workforce
The 383.54-hectare (947.75-acre) master portfolio comprises seven contiguous tracts: Tract A (Ridge & Forest Reserve, 906.53 Ac), Tract B (Phase 1 Residential Enclave with 40 titled condo lots, 5.96 Ac), Tract C (Gateway Commercial Terrace, 13.41 Ac), Tract D (Mid-Elevation Overlook, 11.24 Ac), Tract E (Valley Riverfront, 9.88 Ac), Tract F (Highway Access Node, 0.20 Ac), and Tract G (Commercial Outparcel, 0.53 Ac). Prior to 100% return of the $14.0M LP principal, the Preferred LP / Co-GP Administrative Manager maintains checkbook, escrow, audit, and infrastructure contracting control, while the Founding Sponsor serves as Master Architectural & Visionary Director with funded operational support.
Growth Opportunities & Forward Pipeline
The 5-phase Regenerative Blue-Zone Master Plan dedicates over 50% (500+ acres) to permanent tropical forest conservation, organic agriculture, and equestrian trails, anchoring a 369-home regenerative residential sanctuary, a 33-acre world-class Healing Center, a 60-key luxury eco-wellness resort, and highway commercial frontages. Across Phases 1 through 5 (Months 1 to 72), the project is underwritten to achieve $78,500,000 USD in cumulative gross horizontal sales realization and $60,000,000 USD in net cash flow (ops and CapEx adjusted).
Acquisition Terms & Owner Transition
Offered as $14,000,000 USD in Preferred LP Equity Units ($9.0M land acquisition closing + $2.0M Phase 1 infrastructure & wells + $1.0M grid connectivity & master reserve + $2.0M working capital, legal & reserves, paired with a $1.5M Recycled Lot-Sale Reserve for $6.5M total working liquidity). Structured with an institutional 4-tier European waterfall: 100% priority return of capital to Preferred LPs (with 70/30 working capital recycling up to $1.5M) plus an 8.0% to 10.0% cumulative Preferred Return hurdle prior to GP promote participation, targeting 2.60x to 2.65x LP MOIC ($36.39M to $42.68M total LP distribution), 28.5% to 32.0%+ Net IRR, and a 16 to 20 month payback horizon. Includes an early refinance/buyout option in Months 18 to 30 at a guaranteed 2.00x MOIC ($28.0M) floor with 12.5% residual equity carry. Due diligence expires December 4, 2026, targeting a January 3, 2027 closing.

Key Details

David Mora


Request Information

 BUSINESS
ADVISORS
BUSINESS
ADVISORS
BUSINESS
ADVISORS
BUSINESS
ADVISORS